DRAFT LTC Marketing | A Family Guide
Questions to Ask Your Parents About Care
A practical guide for adult children: how to start the conversation, what to ask, what care costs, how families pay for it, and where to keep the documents that matter.
Educational material. Not connected with or endorsed by the U.S. government or the federal Medicare program.
Start here
Why this conversation matters now
Most families talk about care for the first time in a hospital hallway, after a fall or a diagnosis. In our view, the families who fare best are the ones who talked a year or two earlier, around a kitchen table, while everyone could still weigh in.
The surprise most families share
Many parents assume Medicare will handle it. It generally will not. Medicare does not pay for long-term custodial care, the everyday help with bathing, dressing, eating and getting around that most people actually need.1 Medicare Part A may cover skilled nursing facility care for a limited time, up to 100 days, after a qualifying hospital stay, and only while skilled care is needed.2 That gap is where family savings, family time and family relationships get tested.
Why you, and why now
Adult children often become the care coordinators, the drivers, the bill payers and the people who sign forms. AARP reports that about 29% of family caregivers are also raising children of their own, the so-called sandwich generation.5 In our opinion, a plan made early protects your parents' independence and your own finances, career and health at the same time.
How to use this guide
- Read it yourself first, then share it with siblings so everyone starts from the same facts.
- Pick one or two sections for the first conversation. You do not need to cover everything at once.
- Use the worksheet to take notes, and the organizer to record where documents are kept.
- When you are ready, the free quote comparison at the end of this guide can show what coverage could cost.
Watch for
Signs it may be time to talk
None of these alone means a parent needs care. Two or three together, or a change from how things used to be, is usually worth a gentle conversation.
Around the house
In daily life
In the family
0 of 16 signs checked.
How to begin
Starting the conversation
Parents tend to hear "we need to talk about your care" as "we think you can't manage." The goal is the opposite: to make sure their wishes are the ones that get followed.
Openers that tend to work
"I just put together my own will and health care papers. It made me wonder, have you and Dad done yours?"
"A friend's mom fell last month and nobody knew what she wanted. I'd rather hear it from you now."
"If something happened, I want to do things your way. Can you tell me what your way is?"
"I read that Medicare doesn't cover most long-term care. Did you know that? I didn't."
Do and avoid
| Things that help | Things that tend to backfire |
|---|---|
| Choose a calm, private moment, such as a quiet visit, a drive or a walk | Raising it at a holiday dinner or in front of grandchildren |
| Lead with their wishes and values, not with money | Opening with nursing homes or the cost of care |
| Ask open questions and let silence do some work | Arriving with a finished plan for them to sign |
| Bring siblings in early, even by phone, so no one feels ambushed | One child deciding for everyone, or siblings taking sides |
| Expect several short talks over weeks or months | Treating one conversation as the deadline |
| Write down what you hear and read it back to them | Assuming you will remember the details later |
If a parent says "not now"
That is a normal first answer. Respect it, set a time to come back to it, and share this guide so they can read it privately. In our experience, many parents raise the subject themselves a few weeks later.
Worksheet
Questions to ask, with room for answers
Use these as a menu, not a script. Skip what does not fit and write the answers in your parents' own words.
Wishes and values
Health
Home
Money and coverage
Documents and people
The numbers
What care costs and where it happens
Costs vary widely by state and by city. The national medians below give a sense of scale; your local figures may be higher or lower.
| Setting | What it usually includes | 2025 national median |
|---|---|---|
| Home care (aide) | Help with bathing, dressing, meals, errands and supervision in the parent's own home | $80,080 per year6 |
| Assisted living | Private apartment, meals, activities and help with daily activities in a community setting | $74,400 per year6 |
| Nursing home (private room) | 24-hour supervision and skilled nursing care | $129,575 per year6 |
| Family caregiving | Unpaid help from a spouse, child or relative | No bill, but often real costs in lost income, health and time4 |
How long care can last
LongTermCare.gov estimates that while many people need care for a shorter period, about 20% of people turning 65 will need it for more than five years.3 In our view, that range is exactly why a plan matters: a few months can often be absorbed, but several years can reshape a family's finances.
A quick exercise
Multiply the local yearly cost of the setting your parent prefers by three years. Then ask: where would that money come from, and who would it affect? Write the answer here.
Funding options
How families pay for care
Most families end up using a combination of sources. The right mix depends on age, health, savings and what your parents want to leave behind.
| Option | What to know | Worth asking |
|---|---|---|
| Medicare | Does not pay for long-term custodial care. Part A may cover up to 100 days of skilled nursing facility care after a qualifying hospital stay.1,2 | Is any current care skilled, and for how long? |
| Medicaid | Pays for long-term care for people who meet income and asset limits. Gifts or transfers made within 60 months (five years) of applying can cause a penalty period.7 | Should we speak with an elder law attorney before moving any assets? |
| VA Aid and Attendance | An added monthly amount on a VA pension for wartime veterans and surviving spouses who need help with daily activities, are bedridden, live in a nursing home or have limited eyesight. Apply with VA Form 21-2680.8 | Did Dad or Mom serve during a wartime period? |
| Traditional LTC insurance | Pays benefits for qualifying care. Health questions apply, and it becomes harder to qualify with age: AALTCI reports 47% of applicants aged 70 to 75 are declined or deferred.9 | Is there an existing policy, and what does it pay per day and for how long? |
| Linked-benefit life or annuity | Combines life insurance or an annuity with long-term care benefits, so money not used for care can pass to heirs. | Would a policy that returns value if care is never needed feel better? |
| Self-funding | Paying from savings, income or home equity. In our view this works best with a written plan for which assets are used first. | Which accounts would we draw on, and in what order? |
| Family caregiving | Often the default when nothing else is in place, and frequently the most costly in non-financial ways. | Who in the family is realistically able to help, and for how long? |
For parents 75 and older with savings outside retirement accounts
Many parents in their late 70s and 80s assume it is too late to plan. In our opinion, that is not always true. Some annuities are built to work alongside long-term care benefits under Section 7702B of the tax code, and they can be funded with non-qualified money, meaning savings that are not in an IRA or 401(k), such as CDs, bank savings or an existing annuity. Under federal tax rules, an existing non-qualified annuity may in some cases be exchanged into a contract with long-term care benefits without current tax on the exchange.10
These contracts typically use simpler health questions than traditional coverage, though underwriting still applies and features vary by carrier and state. For families with substantial savings, we believe it is worth asking whether part of a dormant CD or old annuity could be put to work for care. A licensed specialist and your tax advisor can review whether it fits.
Organizer
Documents and contacts
In a crisis, families lose days looking for papers. Fill this in together and keep a copy where at least two family members can find it.
| Document | Why it matters | Where it is kept / who is named |
|---|---|---|
| Durable power of attorney (financial) | Lets a trusted person pay bills and manage accounts if a parent cannot | |
| Health care surrogate or proxy | Names who makes medical decisions if a parent cannot speak for themselves | |
| Living will / advance directive | Records wishes about life-sustaining treatment | |
| HIPAA authorization | Allows doctors to share information with named family members | |
| Will and any trust | Directs how assets pass, and who is in charge | |
| Insurance policies (LTC, life, annuity) | Benefit amounts, waiting periods and claim phone numbers | |
| Medicare, supplemental and drug plan cards | Needed at every admission and appointment | |
| Military discharge papers (DD-214) | Required for VA benefits | |
| Bank, investment and retirement accounts | Who to call, and how bills are paid | |
| Passwords and digital accounts | Email, online banking and phone access |
For safety, write down where passwords are kept rather than the passwords themselves.
Key contacts
| Contact | Name | Phone |
|---|---|---|
| Primary doctor | ||
| Attorney | ||
| Accountant or tax advisor | ||
| Financial advisor | ||
| Insurance agent | ||
| Nearest family member |
For you
If you are, or may become, the caregiver
- Share the load early. Agree on who handles money, who handles medical visits and who checks in each week.
- Keep a simple care log of medications, appointments and changes you notice. It helps doctors and siblings alike.
- Ask your employer about family leave and caregiver benefits before you need them.
- Look into respite care and local Area Agency on Aging services so you can rest.
- Make your own plan. In our view, one of the kindest things you can do for your children is to have this conversation about yourself, too.
Next step
Get a free, no‑obligation quote comparison
Once you know what your parents want, the next question is how to pay for it. A free quote comparison shows what long-term care coverage could cost for your mom or dad, or for you, based on age, health and budget.
- No cost and no obligation to buy
- A side-by-side comparison, not a generic rate sheet
- A response within one business day from a licensed insurance professional
Scan the code or visit DraftLTCMarketing.com. Questions? Call [Agent - Advisor Name], CLTC, at (xxx)xxx-xxxx.
Your privacy and your choice
Requesting a quote does not commit you to anything. A licensed insurance professional from Your Brokerage Agency Name will contact you only about your request, and you can opt out at any time. This is not an offer of insurance; final eligibility is subject to underwriting, and features and availability vary by carrier and state.
Share this guide
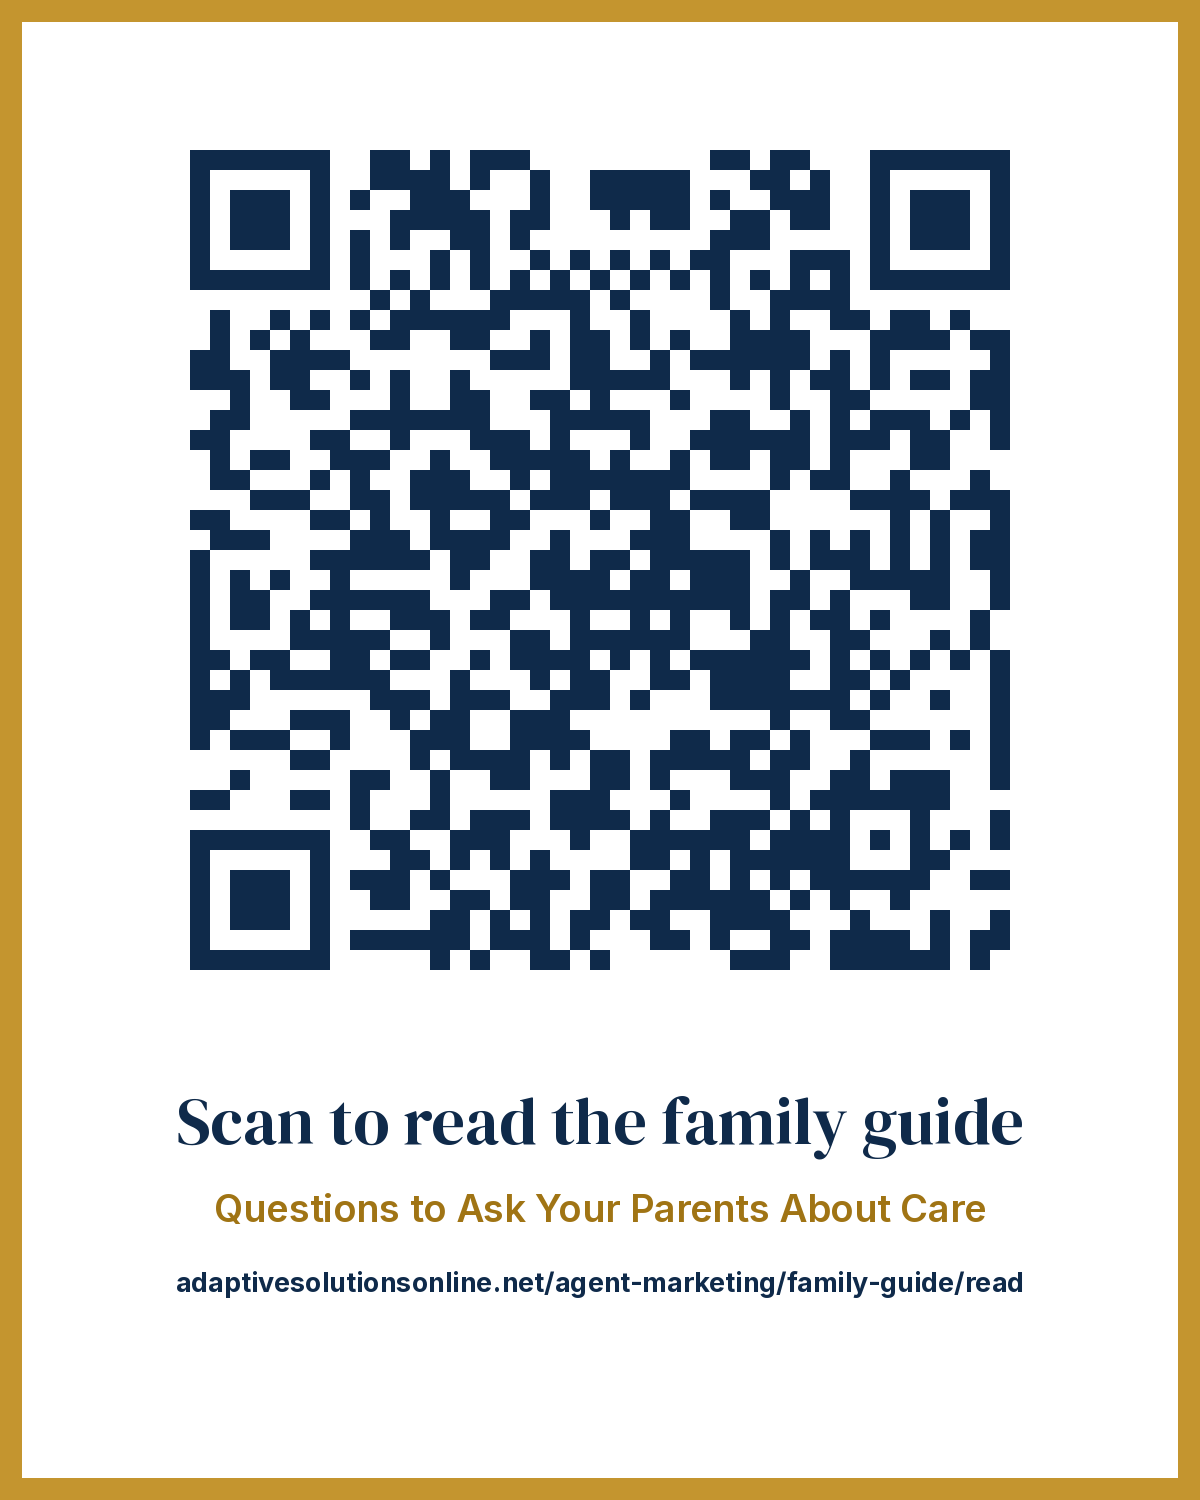
Scan to read the family guide
Send this code to a brother, sister or anyone else helping your parents. Scanning it opens this online version of Questions to Ask Your Parents About Care, where they can fill it in, print it or download the PDF.
Or visit adaptivesolutionsonline.net/agent-marketing/family-guide/read.
Notes
Sources and important information
Important: This guide is educational and reflects the opinions of its authors. It is not legal, tax, financial or medical advice; please consult a qualified professional about your situation. Insurance and annuity products are offered only through licensed agents, and features, availability and underwriting vary by carrier and state. This material is not connected with or endorsed by the U.S. government or the federal Medicare program, and it is not about any Medicare Advantage plan. Distributed by Your Brokerage Agency Name, [City, State]. Cost figures are national medians and will vary by location.
Sources
- Medicare.gov, Long-term care coverage. https://www.medicare.gov/coverage/long-term-care
- Medicare.gov, Nursing home care coverage. https://www.medicare.gov/coverage/nursing-home-care
- ACL / LongTermCare.gov, How Much Care Will You Need? https://acl.gov/ltc/basic-needs/how-much-care-will-you-need
- AARP, New Report Reveals Crisis Point for America's 63 Million Family Caregivers (2025). https://www.aarp.org/press/releases/2025-07-24-new-report-reveals-crisis-point-for-americas-63-million-family-caregivers/
- AARP Public Policy Institute, Caregiving in the US 2025: Sandwich Generation. https://www.aarp.org/pri/topics/ltss/family-caregiving/caregiving-in-the-us-sandwich-generation/
- CareScout 2025 Cost of Care Survey results. https://investor.genworth.com/news-events/press-releases/detail/1054/carescout-releases-2025-cost-of-care-survey-results
- CMS, Deficit Reduction Act: Transfer of Assets backgrounder. https://www.cms.gov/regulations-and-guidance/legislation/deficitreductionact/downloads/toabackgrounder.pdf
- VA.gov, VA Aid and Attendance benefits and Housebound allowance. https://www.va.gov/pension/aid-attendance-housebound/
- AALTCI, Nearly Half of Oldest LTC Insurance Applicants Declined. https://www.aaltci.org/news/long-term-care-insurance-association-news/applicants-declined
- IRS Notice 2011-68 (annuity and long-term care contract tax treatment). https://www.irs.gov/pub/irs-drop/n-11-68.pdf